"I Should Have Bought in 2020." Here Is What the Numbers Say
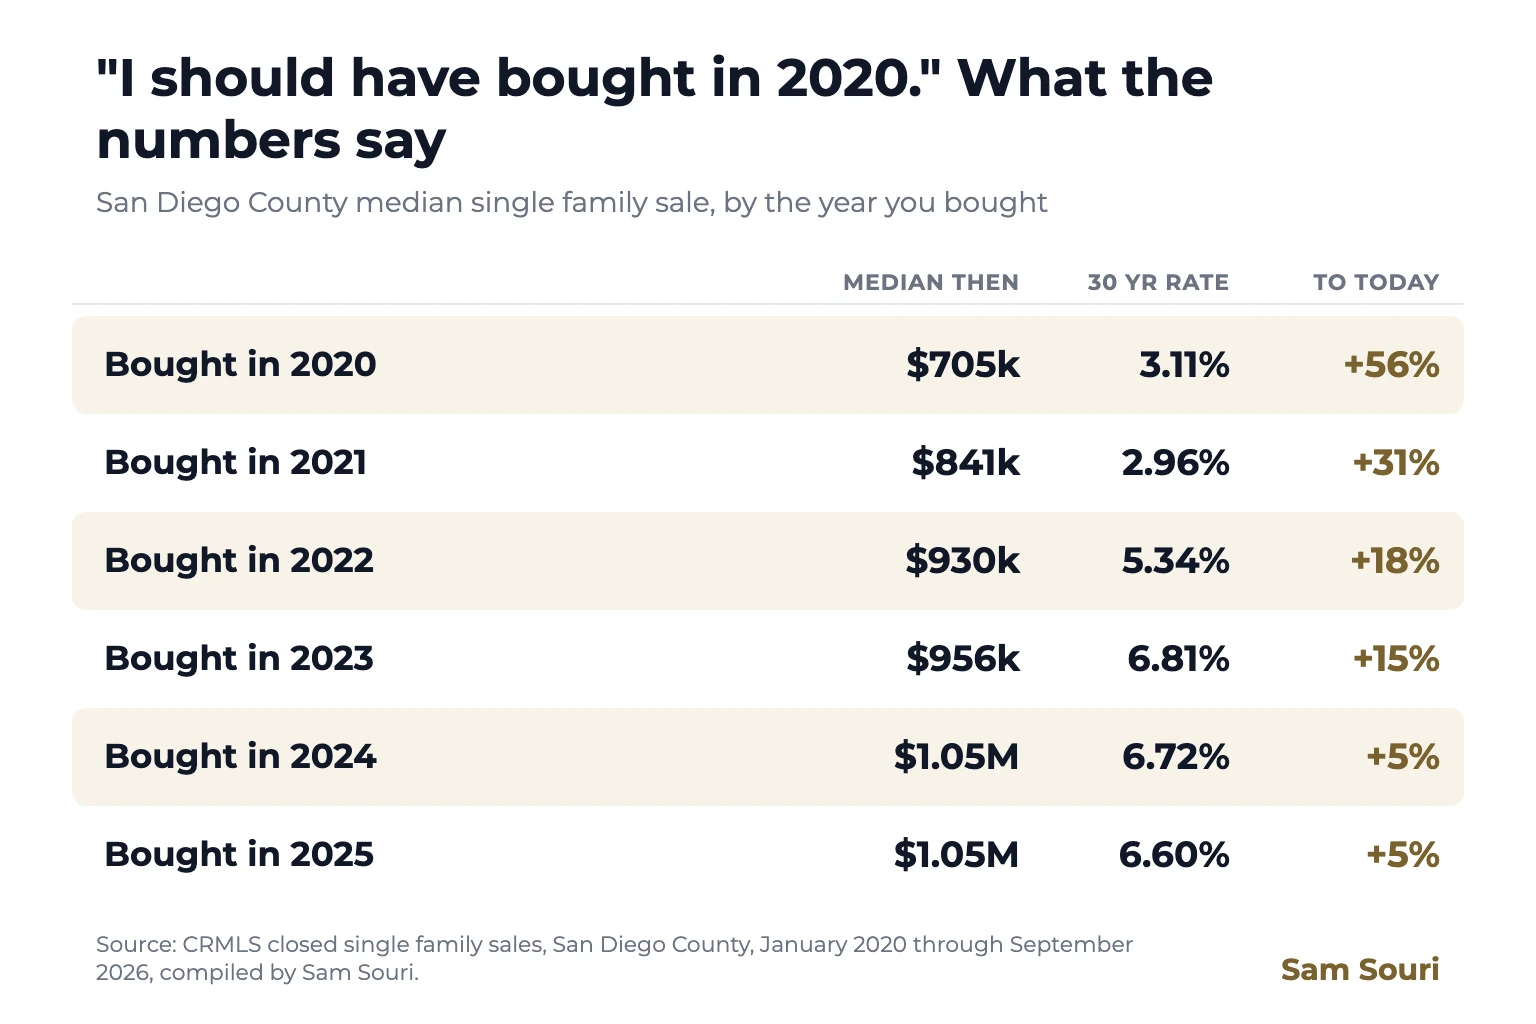
"I should have bought in 2020." It is one of the most common things buyers tell me right now, and it is easy to see why. The typical single family home in San Diego County sold for $705k in 2020. So far in 2026, it sells for $1.10M. That is a gain of 56% in six years.
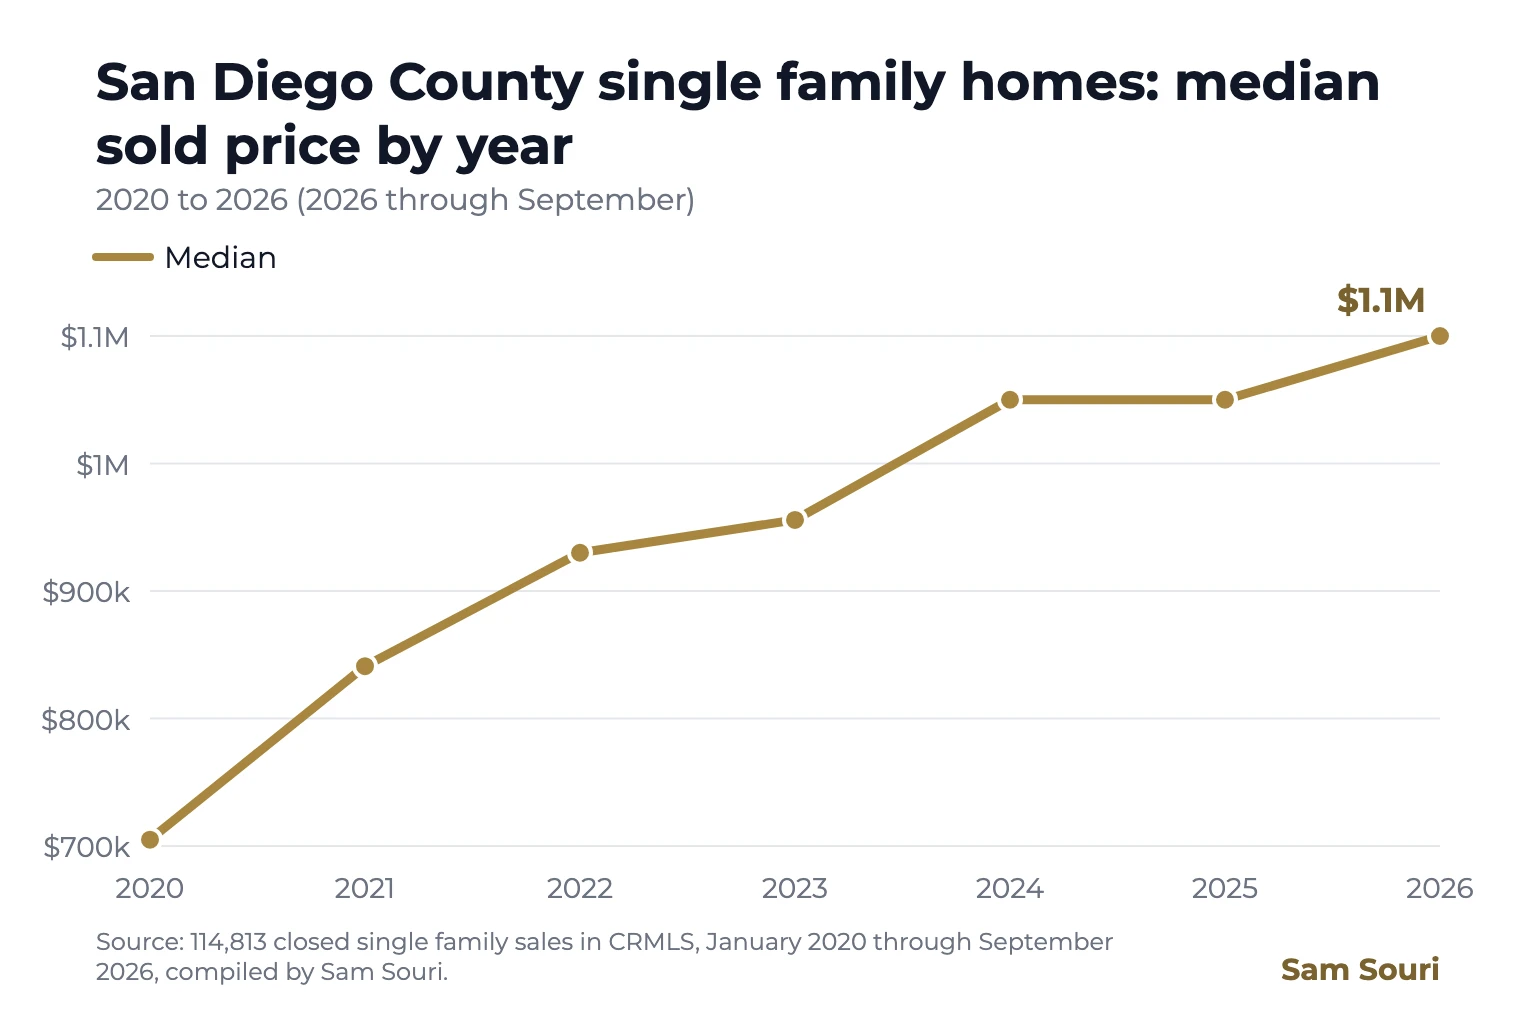
But hindsight makes it look a lot easier than it was. Here is what the closed sales actually show, and what I think matters more than timing.
Nobody felt like buying in 2020
2020 came with a pandemic, lockdowns and plenty of headlines predicting a crash. Most people who could have bought were waiting to see what would happen. Prices climbed through the year anyway, and the buyers who waited for things to feel certain ended up paying more by the end of it.
Every year since had its own reason to wait
The table below shows what the typical San Diego County house sold for in each year, the average 30 year mortgage rate that year, and the monthly principal and interest with 20% down.
| Bought in | Median sale price | 30 year rate | Payment at 20% down | Change to today |
|---|---|---|---|---|
| 2020 | $705k | 3.11% | $2,411 | +56% |
| 2021 | $841k | 2.96% | $2,822 | +31% |
| 2022 | $930k | 5.34% | $4,150 | +18% |
| 2023 | $956k | 6.81% | $4,990 | +15% |
| 2024 | $1.05M | 6.72% | $5,431 | +5% |
| 2025 | $1.05M | 6.60% | $5,365 | +5% |
| 2026 so far | $1.10M | 7.40% today | $6,093 |
In 2021, prices felt too high. In 2022, rates jumped from about 3% to an average of 5.34%. After that, a lot of buyers decided to wait for a crash that never came. Yet a buyer from every one of those years is ahead today. Even 2024 and 2025 buyers are up about 5%, and that is before counting the principal they have paid down.
The real cost of waiting
Waiting for certainty did not just mean a higher price. It also meant a higher rate. The typical house cost about $2,411 a month in principal and interest in 2020. Today it costs about $6,093 a month, before taxes and insurance. That is $3,682 more every month for the same typical home.
You can see the zip by zip version of the price story in my post on the San Diego zips where home prices rose most since 2020.
Prices can fall too
None of this means prices only go up. San Diego prices dropped hard after 2006. The owners who could hold on through it recovered. The owners who were forced to sell in the first few years did not. That is the real lesson. The year you buy matters less than whether you can stay.
What actually matters
If you are thinking about buying, these are the questions I would ask before worrying about timing:
- Does the payment work for my budget today, at today's rate?
- Do I plan to stay five years or more?
- Can I treat refinancing as a bonus if rates fall, instead of counting on it?
If the answer to all three is yes, waiting for the perfect moment usually costs more than it saves. You can see what is for sale today on current listings.
Thinking about buying this year? Reach out and I will run the real numbers for your budget and the zips you like.
Thinking about a move in San Diego?
Contact SamGet the monthly letter
San Diego market notes from Sam, plus investor insights from Prop2Profit.
1-2 emails a month. Unsubscribe anytime.