San Diego Payment Math at 7.03%: $800k, $1.2M, and $1.8M Buyer Scenarios
Rate Check and Why It Matters
The average 30‑year fixed sits near 7.03%. In San Diego, that payment drives what you can comfortably buy from Clairemont entry homes to La Jolla view condos. County inventory sits at 4,675 homes, with a median list price of $949,000 and 41 days on market. Example: 2334 Division Street in National City is listed at $949,000 at $503 per sqft, a snapshot of the current mid-range.
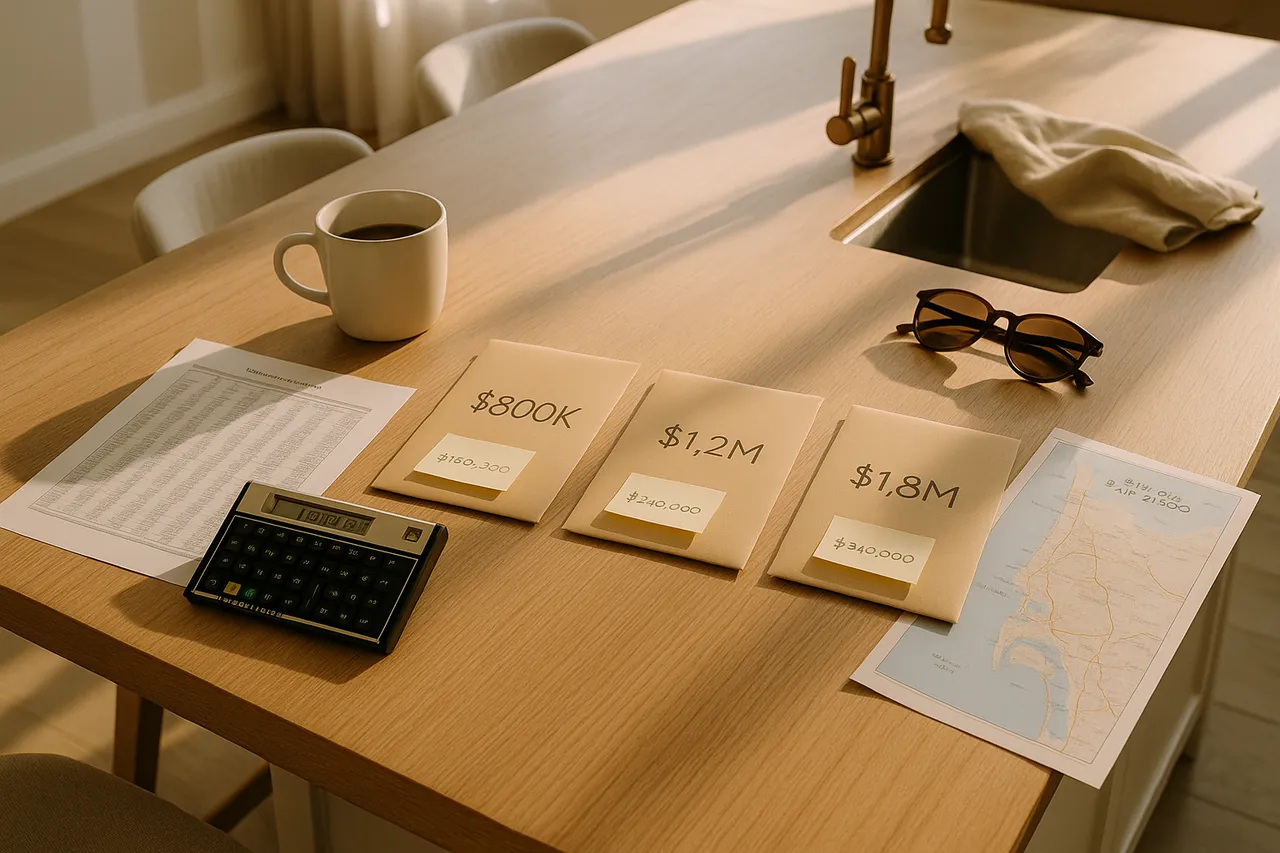
Below I show three price points buyers ask me about weekly in Carlsbad, Encinitas, and Carmel Valley. I use common terms: 20% down, 30‑year fixed at 7.03%, 1.25% property tax, 0.25% insurance, and no HOA for simplicity. Your numbers change with HOA, Mello‑Roos, or different down payments.
Three Realistic Scenarios at 7.03%
Assumptions: principal and interest are based on loan amount after 20% down. Taxes and insurance are rough but typical countywide.
-
$800,000 purchase
- Down: $160,000, Loan: $640,000
- P&I at 7.03%: about $4,260
- Taxes: $833, Insurance: $167
- Estimated total: about $5,260 per month
-
$1,200,000 purchase
- Down: $240,000, Loan: $960,000
- P&I at 7.03%: about $6,390
- Taxes: $1,250, Insurance: $250
- Estimated total: about $7,890 per month
-
$1,800,000 purchase
- Down: $360,000, Loan: $1,440,000
- P&I at 7.03%: about $9,580
- Taxes: $1,875, Insurance: $375
- Estimated total: about $11,830 per month
Where this fits locally:
- Around $800k: think central condos or smaller SFRs in Clairemont or Vista. 750 Breeze Hill Road #121 in Vista is listed at $449,999, a lower price point that shows how payments can shift with HOAs.
- Around $1.2M: family homes in San Marcos or parts of Carlsbad. 690 Jay Court in San Marcos at $1,149,999 is right in the zone.
- Around $1.8M: larger homes in Encinitas or Carmel Valley, close to Del Mar Highlands and Torrey Pines High.
Buy‑downs, ARMs, and Points: What Pays Off
- Temporary 2‑1 buy‑down: Year 1 rate drops by 2%, Year 2 by 1%, then back to 7.03%. On a $960k loan, Year 1 P&I lands near 5.03% for about $5,180, saving around $1,200 per month in year one. Great if you expect higher income soon or a refinance window.
- Permanent points: One point costs 1% of the loan. On $960k, one point is $9,600. If that drops your rate about 0.25%, P&I might fall roughly $150 per month. Break‑even is about 64 months. If you plan to hold 6‑7 years, points can pencil. If a refi is likely sooner, skip it.
- 7‑year ARM: Often 0.5% lower than fixed. On $960k, a 6.5% start rate drops P&I to about $6,070, saving around $320 per month. Best for buyers who will sell, refi, or receive RSU refresh cycles before year 8, common in Carmel Valley biotech households.
Street‑Level Advice
- Keep offers rate‑aware: Ask for seller credits to fund a 2‑1 buy‑down on homes that have sat near the median, like properties around the $949,000 mark, for example Division Street. Credits can beat a small price cut for your monthly cash flow.
- Shop neighborhoods, not just rate: Payment parity can shift doors. A $1.2M home in Escondido might rival a smaller place in Encinitas, yet both keep you close to North County jobs.
- Lifestyle filter: If you dream of Coronado mornings on Orange Avenue or surfing Windansea in La Jolla, get pre‑approved to your comfort number first, then target micro‑pockets that match it.
Looking for help with mortgage strategy and neighborhood fit?
Contact SamGet the monthly letter
San Diego market notes from Sam, plus investor insights from Prop2Profit.
1-2 emails a month. Unsubscribe anytime.